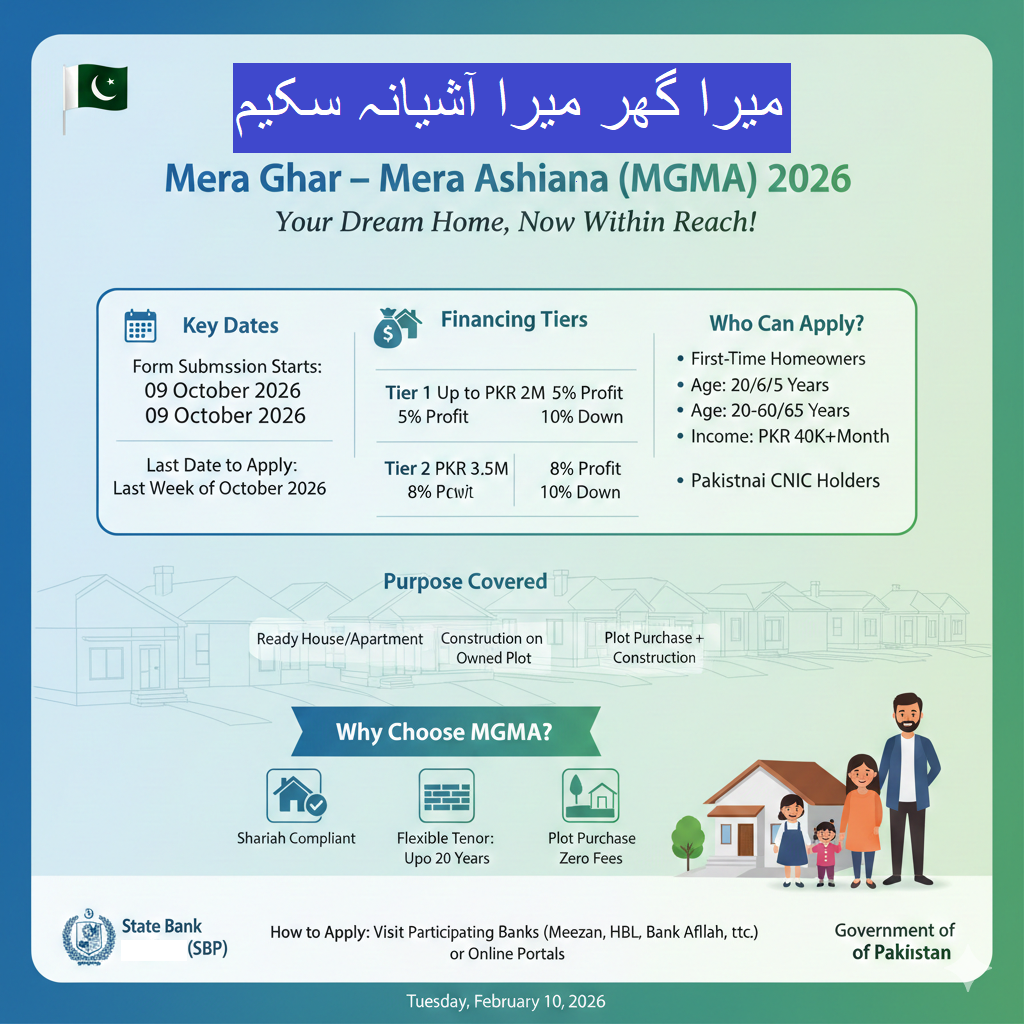
To encourage housing finance in low-cost housing sector, the Government of Pakistan has announced a profit subsidy and risk sharing scheme named as “Mera Ghar – Mera Ashiana” (MGMA). The Complete Home Financing facility is available from mutliple banks within the ambit of its easy home – mera ghar mera ashiyana product, which is an ideal Islamic housing finance solution to either construct or buy a completed house, in a completely Shariah-compliant manner under the concept of Diminishing Musharakah.
Mera Ghar Mera Ashiana Scheme 2026 Apply Online – Now
The Mera Ghar Mera Ashiana Housing Scheme is a housing project to support first time home buyers, as they will be provided affordable housing with the help of this initiative through mortgage financing on soft terms. It usually aids in buying a house or an apartment, building with owned land, or taking a plot along with construction. The scheme targets to low/ middle income households and is available through participating banks and housing finance companies.
Note: There could be variance in the program details from time to time and based on location. Be sure to check current terms with your bank or official portal when applying.
Mera Ghar Mera Ashiana Housing Scheme 2026 Dates:
| Title: | Mera Ghar Mera Ashiana Housing Scheme 2026 |
|---|---|
| Scheme | Mera Ghar Mera Ashiana MGMA |
| Form Start Date | 09 October 2026 |
| Last Date | Last Week Of October 2026 |
| Posted By | seccap.com.pk |
| Age Limit | 20 Year to 60 Years |
Who Is Eligible For Mera Ghar Mera Ashiana Scheme?
Income and Residency
- For low‑ to middle‑income earner.
- Original national ID and proof of residence/address.
- Reported earnings from employment or self‑employment.
First‑Time Homeownership Requirement
- Applicants should not already have invested in a residential property.
- One per Family/Household (subject to new rules).
Type of dwelling and its size limitation (as a property category)
- Dwelling units in the form of houses (or parts thereof) and/or apartments under established size limits, such as small to mid‑sized units.
- In case of construction – land/ plot should be in the name of applicant / co-applicant and local by laws must be adhered to.
Qualification Criteria
| Parameters | Details |
| Allowable Financing Cities | All cities of Pakistan where branch network is running of MEZAN BANK |
| Age of Applicant / Co-applicant |
|
| Monthly Income | There is no income limit for the formal sector, but maximum debt burden ratio up to 50% will be considered at the time of sanctioning. |
| Employment / Business Tenor | Salaried Individuals:
Self-Employed / Business Person: Atleast 2-3 years experience in current business/ industry. |
| Co-applicant Income Clubbing |
|
Mera Ghar Mera Ashiana Housing Scheme 2026 Key Benefits and Features
Financing Options Covered
- Purchase of ready house/apartment.
- Construction on owned plot.
- Plot purchase cum construction (With a time bound requirement of construction).
Subsidy and Pricing Basics
- Mark-up/Fixed rates subsidy for a period during the loan tenor.
- Prices commonly come in and out of “tiers” depending on size of the unit and amount of loan.
- Some banks might offer some reduced processing fees for participants.
Loan Tenure and Equity
- How Long You Can Take to Repay the Loan: Tenure from usually up to 20 years (depends on lenders).
- Equity/down payment requirements are typically less than with other mortgages.
- Higher loan‑to‑value (LTV) ratios are available to tiers.
Product Features & Benefits
| Tiers | Maximum Financing | Minimum Contribution from Customer | Rental Rate |
|---|---|---|---|
| Tier 1 | Up to PKR 2 million | 10% of property value | 5% for first 10 years and variable at KIBOR + 3% for subsequent years |
| Tier 2 | Above PKR 2 million up to PKR 3.5 million | 10% of property value | 8% for first 10 years and variable at KIBOR + 3% for subsequent years |
| Financing Tenure | Maximum 20-year financing tenure | ||
| Size of Housing Unit | House of up to 5 Marla or flat/apartment of up to 1360 sq ft | ||
| Maximum Price of Housing Unit | No capping | ||
Mera Ghar Mera Ashiana MGMA Scheme Required Documents Checklist
- CNIC of applicant and co‑applicant (if any)
- Recent passport‑size photographs
- Proof of income:
- Salaried: Offer letter, payslips (3–6 months), bank statements etc.
- Self‑employed customers: · business registration, tax returns, bank statements
- Residency documents: utility bill, lease agreement, etc.
- Property documents:
- For sale: Purchase agreement, title/ownership proof, allotment letter, sanctioned maps
- For building: housing title, approved house plan, cost estimate/BOQ, contractor details
- Reportage de credit ) mz. sex clubs in london as requested by bank)
- Any other such forms as required by the participating lender
How To Apply Online For Mera Ghar Mera Ashiana Housing Scheme 2026
Visit your closest branch of any Bank Ltd that given below for further details on criteria, documentation requirements and the easy application process under the Mera Ghar – Mera Ashiana scheme.
| Banks: | Links |
| Meezan Bank | Apply Online Now |
| Khushhali Microfinance Bank branch | Apply Online Now |
| HBFC Home Finance | Apply Online Now |
| Allied Bank | Apply Online Now |
| MCB Islamic Bank | Apply Online Now |
| SBP State Bank Of Punjab | Apply Online Now |
| bank Al Habib | Apply Online Now |
How to Increase Your Approval Odds in Mera Ghar Mera Ashiana Housing Scheme
- Maintain a low debt‑to‑income ratio; pay down high‑interest debts before applying.
- Be employed and/or stable income for a minimum of 6 to 12 months.
- Provide the loan with a co‑applicant (spouse/parent) to enhance income and credit profile.
- Opt for properties that have clear titles and approved maps so you do not face legal flags later.
- Offer thorough, clear documentation; discrepancies inspire prevention.
Common Mistakes to Avoid
- Applying without checking that the current size of property values/purchase prices.
- Under-declaring income or presenting us with inconsistent bank statements.
- Selecting unapproved or disputed properties.
- Failure to pay attention to the construction schedule in plot‑plus‑construction cases.
FAQs Mera Ghar Mera Ashiana Housing Scheme
Q1: Am i eligible if I already own part of a property?
Traditionally, the plan is for first‑time home buyers. Partial ownership could be a disqualifier — check with your bank.
Q2: Are rates/mark-up fixed for the whole period?
Frequently discounted for some period of time, then return to the non-discount rate. Request the current tier structure from your lender.
Q3: Can overseas Pakistanis apply?
When the remittance is sent, it can be credited to account number with similar documentation from receiver’s side; some banks permit payment without any such detail. Policies vary by lender.
Q4: What size properties are permitted?
Size caps are generally for houses and apartments on the small side. Verify the current limits for your city and tier.
Q5: Is early repayment allowed?
A lot of lenders permit prepayment; a few schemes waive penalties. Verify current policy before signing.
Q6: How long is the approval process?
About 2-6 weeks, based on completeness of documentation, valuation, and government verification.
Final Thoughts
Mera Ghar Mera Ashiana Housing Scheme can reduce the cost of purchasing or constructing your first home significantly. Pay attention to eligibility features, all required documents and is housing in compliance. Check the most recent rates, size caps and lender policies before committing.